In brief: penny drop vs penny-less verification is a trade-off between certainty and cost. Penny drop sends a token credit to prove the account can receive money; penny-less confirms the account and name without moving money.
On this page
Before disbursing a loan, processing a refund, or paying out a vendor, businesses need to confirm that the bank account they're sending money to actually belongs to the person or company they think it does. Two common approaches handle this: penny drop and penny-less verification.
What Is Penny Drop Verification?
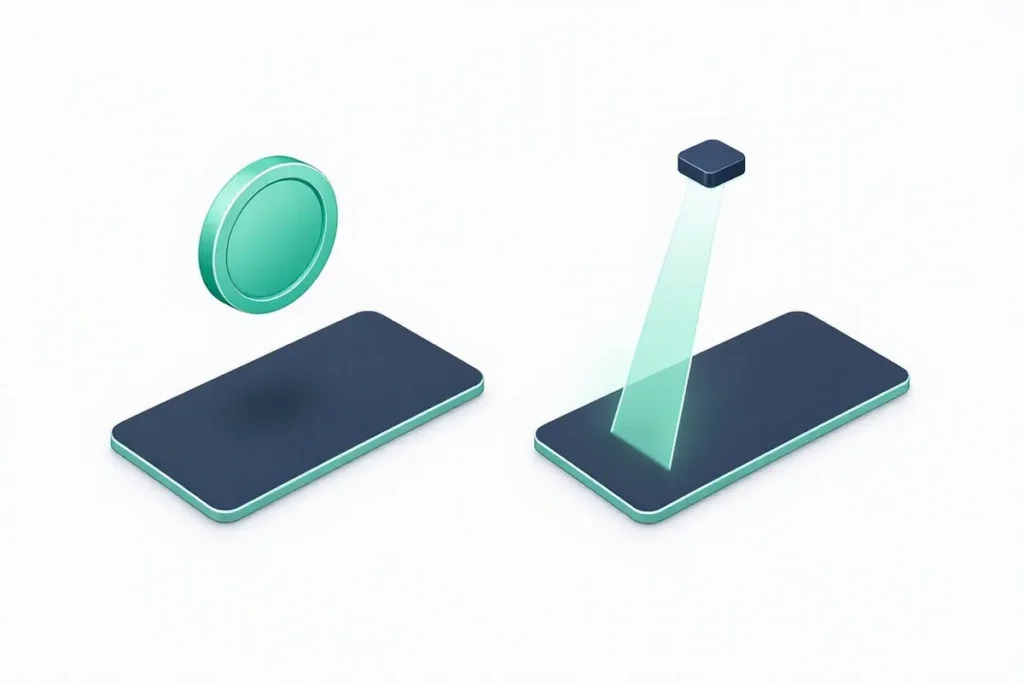
Penny drop verification deposits a small amount — typically ₹1 — into the target bank account and retrieves the registered account holder name from the receiving bank in response. That name is then matched against the name on file to confirm ownership.
- Pros — highly reliable since it uses an actual live transaction; widely supported across banks.
- Cons — takes a few seconds to a few minutes to complete, and involves an actual (small) money transfer each time.
What Is Penny-less Verification?
Penny-less (or "penny-free") verification confirms account details using the bank's account validation APIs directly, without moving any money. It checks the account number and IFSC against the bank's records and returns the account holder name instantly.
- Pros — instant results with no actual transaction required, lower cost per check at scale.
- Cons — depends on bank API availability and coverage; not every bank supports it equally well.
Which Should You Use?
For high-volume, latency-sensitive use cases like instant loan disbursal or real-time payouts, penny-less verification is usually faster and cheaper. For scenarios where absolute certainty matters more than speed — like large one-time payouts — penny drop's use of an actual transaction can offer additional assurance.
How Veriqos Technologies Helps
Veriqos Technologies offers both penny drop and penny-less bank account verification through a single API, letting businesses choose the right method per use case — or combine both for a layered verification approach — without integrating separately with each bank.
Choosing between penny drop vs penny-less verification in practice
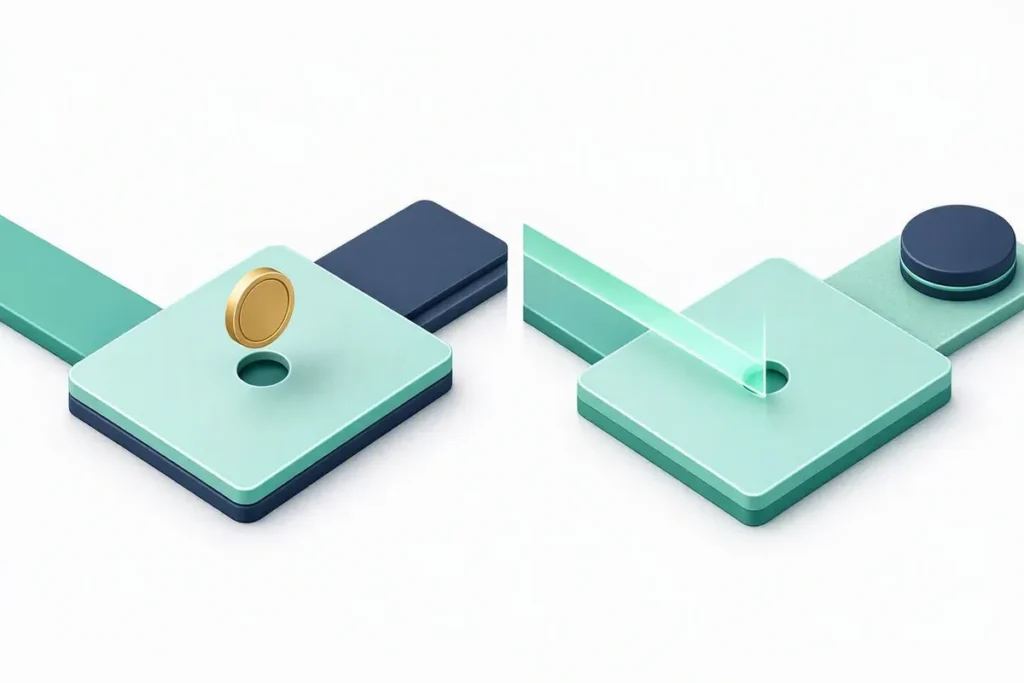
Many teams do not have to choose just one. A common pattern is to run penny-less verification by default, because it is faster and cheaper at scale, and fall back to penny drop when a penny-less check cannot return a result for a particular bank. For very large payouts, some teams prefer penny drop even when penny-less is available, because it confirms the account can receive a credit at that moment. Whichever you use, compare the returned name with your customer’s verified name, since that comparison is what actually protects the payout. Thinking about penny drop vs penny-less verification as a combined strategy, rather than an either-or decision, usually gives the best coverage.
Conclusion
Neither method is universally "better" — the right choice depends on your speed requirements, transaction volume, and risk tolerance. Many mature fintechs use penny-less checks as the default and fall back to penny drop for edge cases where bank API coverage is incomplete.
Related verification APIs
- Penny Drop Verification API — Verify bank account ownership instantly with Veriqos Technologies’ Penny Drop Validation API, performing a secure ₹1…
- Penny-less Bank Account Verification API — Verify bank accounts in real time using the account number, IFSC code, and account holder name
Building this into a banks & nbfcs workflow? See Veriqos Technologies for Banks & NBFCs, or browse the full verification API marketplace.
More about Penny Drop vs Penny-less Verification
To learn more about Penny Drop vs Penny-less Verification, explore our Bank Account Verification API and Penny Drop Verification API, or talk to our team. For the official source, see the Reserve Bank of India website.